Verified Online Business Hit by Square Suspension Without Explanation
A marketing firm that provided all required documents to Square found its account frozen and its appeal denied after the company missed its own response deadline.
By Gavin Wilson ·
A small business that specializes in marketing and search engine optimization for other companies recently experienced a disruption that left its owners feeling blindsided. The firm operates primarily online and had gone through every step of the verification process with Square, the payment processing company. They submitted identification documents and linked a valid bank account. The business also provided the Employer Identification Number document directly from the Internal Revenue Service.
To ensure the connection between the bank and the Square account was secure, the firm used third party software to link them. They also produced the formation documents for their limited liability company. Most importantly, they held a valid contract with a client for the full sum of the money in question. Despite having all these elements in place, Square suspended the account.
The suspension was not caused by a missing document. The bank account did not fail verification. The IRS did not flag the EIN as fake. Instead, the company relied on a rule that the business owners described as nonexistent. This rule was not even listed as a standard reason for suspension in their documentation. The business had not broken this rule because the rule itself did not appear to exist in the public terms. However, the automated system had made its decision, and it did not seem open to questions.
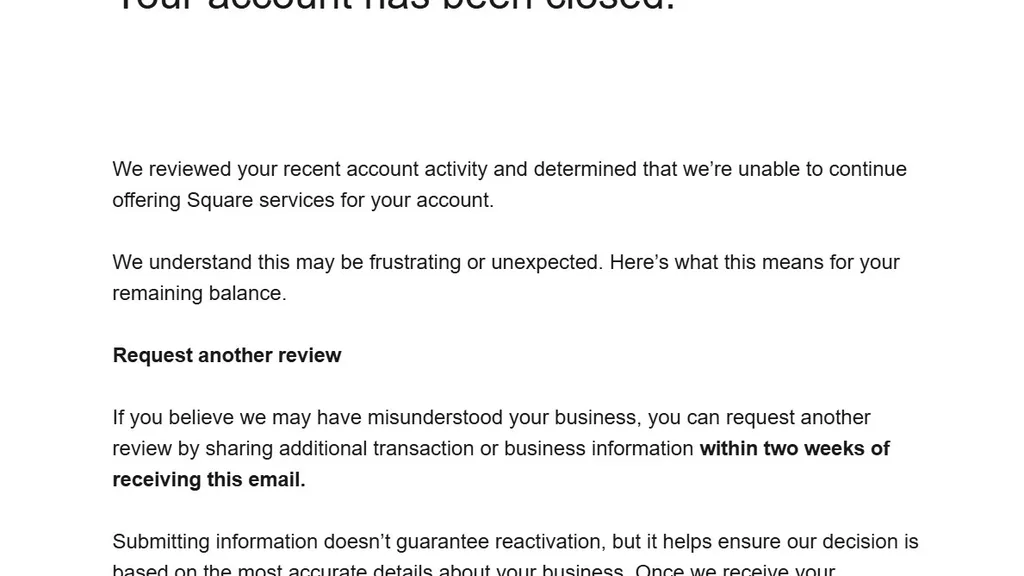
The business owners decided to appeal the suspension. Square promised a response within ten days. It took two weeks for a reply to arrive. When the response finally came, it was a denial. There was no explanation attached to the denial. There was no reason provided for the initial suspension or the subsequent rejection of the appeal. There was no human being to call, no physical office to visit, and no face to look at while receiving the news.
The outcome was simply a denial generated by a system. The business had provided its identity, tax documents, bank account details, and a contract proving the money was real and the client was legitimate. In return, they received a suspension with no stated cause and an appeal that ended without a word.
The frustration for small business owners stems from the specific language found in Square’s own contracts. These documents are written in plain language on the company’s website. Section 12 of the General Terms of Service states that the company may terminate the terms or suspend the account at any time for any reason. This phrasing implies that a specific reason is optional.
Section 13, which deals with the effect of termination, adds that the company will not be liable for compensation, reimbursement, or damages for any termination or suspension of services. This clause allows the company to hold a business’s money and disrupt operations without financial liability.
The Payment Terms contain similar provisions. Section 12 states that the company may defer payout or restrict access to proceeds, either temporarily or indefinitely. This means that revenue from a client who has already paid can remain in the company’s account while the system decides the fate of the merchant. Section 14 mentions a Reserve for Holding Funds. It says the company may require a reserve for any reason related to the use of services. The amount of this reserve is determined reasonably by the company alone, not by a bank, regulator, or judge.
A notable detail appears in Section 1 of the Payment Terms. It opens with the statement that the company is not a bank. It identifies itself as a payment facilitator and a software platform that processes payments. This distinction is significant because traditional banks are subject to specific regulatory rules and must often explain their actions. They are regulated entities that hold customer funds. Square operates as a software company with a suspension button. The contract suggests this button has no off switch for the merchant.
When merchants try to fight these decisions, the contract outlines the process. Section 22 of the General Terms prohibits class actions and jury trials. It requires individual arbitration in Oakland, California. Section 19 caps the total liability of the company at the fees earned from the merchant in the three months before the problem occurred, or five hundred dollars, whichever is greater. This cap suggests that the maximum value of the business to the company is five hundred dollars.
Section 7 adds that if there is a dispute about who owns the account, the company will be the sole arbiter of the dispute in its sole discretion. The decision is final and binding on all parties. This arrangement places the company in the role of player, referee, and stadium simultaneously.
The situation highlights a shift in how online commerce is handled. A company that is not a bank is acting with the power of one. An automation system scrutinizes businesses with zero reason and zero explanation. A merchant who completed every verification step is suspended by a rule that is not even a listed reason for suspension. The appeal process takes twice as long as promised and ends without a word.
The business cannot easily dispute the outcome because doing so means entering arbitration in the company’s city, under its rules, for a prize capped at five hundred dollars. Square’s Payment Terms also include a list of unsupported industries. Item 6 on that list is direct marketing or subscription offers or services. A marketing and SEO firm is close to this category. The system may not need the rule to be strictly true. It may only need the rule to be convenient for the algorithm.
Traditional banking structures require explanations. Regulators require companies to show their work. Human beings in these roles often have to look a customer in the eye and explain a decision. In the current model, there is no one to look at. There is a dashboard. There is a denial. There is a machine that has never met the business, never read the specific contract, and never spoken to the client. The decision is already made.
This setup is not just a payment processor. It is a toll booth on the only road a small business has. It is run by a company that is not a bank. It is governed by a contract that says the company can do whatever it wants, whenever it wants, for any reason, and owe the merchant nothing for it.
The verified business in this case did everything right. It provided the ID, the IRS document, the LLC papers, and the client contract. Square did not need any of that to make its decision. That is the core of the issue. The system operates independently of the merchant’s compliance.
Until a company that is not a bank starts acting like one, every small business in the country is one algorithm away from losing its money and its account. The loss comes with no reason given and no explanation owed. The current system relies on silence and speed. The merchant is left with a frozen account and a contract that limits their recourse.
The experience of this marketing firm serves as a clear example of the risks involved in relying on these platforms. The business owners followed the protocol. They verified every piece of information. They linked the bank account through secure software. They had a signed contract for the full sum. And yet, the suspension happened. The appeal was denied two weeks after the initial request, missing the ten day promise.
The denial was brief. It contained no human touch. It offered no path to resolution other than arbitration. The money from the client sat in the company’s account. The business could not access its own revenue. The reason for the suspension was a rule that did not appear in the list of standard suspension causes.
This incident is not just about one company. It is about the structure of modern online payments. The power is concentrated in the hands of a software provider that admits it is not a bank. The contract terms give this provider wide latitude. They can suspend an account for any reason. They can hold funds indefinitely. They can cap their liability at a low amount. They can force arbitration in a specific location.
Small business owners are often unaware of these terms until they face a suspension. They assume that providing complete and accurate information will protect them. They assume that if the documents are in order, the money will flow. The reality is that the system can override these safeguards. The verification process is a gate, but the suspension button is the lock.
The marketing firm had to navigate this process alone. There was no phone support to call. There was no local branch to visit. There was only the digital interface and the written contract. The contract said the company could do what it did. The contract said the company owed no compensation. The contract said the company would be the final judge of any dispute.
More Business · Business Watchdog · Report a business · Got a Story?